Why Insurance and Estate Planning Are Two Halves of the Same Strategy
Most families treat insurance and estate planning as separate projects handled by separate people at separate times. The insurance agent shows up when a policy is due for renewal. The estate attorney shows up when a will needs updating. The two conversations rarely overlap, and that separation is where a great deal of value gets lost. Insurance without estate planning often creates liquidity that has no structure to receive it, and estate planning without insurance often creates a beautiful plan that the family cannot afford to fund. The families who protect wealth most effectively are the ones who treat the two as a single system, designed together and reviewed together.
The reason the combination matters is that estate planning is fundamentally about transferring wealth, and transfer almost always costs money. Estate taxes, probate fees, administrative expenses, and the cost of settling a business or a property portfolio all take a bite out of what the family keeps. Insurance is one of the few tools that can create the liquidity to pay those costs without forcing the sale of the assets the family wants to keep. That is the practical core of wealth protection insurance: it does not prevent the event, but it makes the financial consequences of the event manageable.
There is also a timing dimension that families often underestimate. Estate taxes are due relatively quickly after death, often within nine months in the United States, while assets such as real estate, private businesses, and illiquid investments can take years to sell. A family that inherits a valuable business and a large estate tax bill but no cash has a serious problem, even if the balance sheet looks strong on paper. Life insurance held in the right structure can solve that problem directly, providing the cash to pay the tax while the family decides what to do with the underlying assets. That is one of the clearest examples of life insurance estate planning working as intended.
The reverse is also true. Insurance without planning can create its own problems. A large death benefit paid directly to beneficiaries can be mismanaged, spent quickly, or exposed to creditors and divorce. A policy owned by the insured can be included in the taxable estate, which defeats part of the purpose. A policy with outdated beneficiary designations can send money to the wrong people. The fix is to integrate the policy into the estate plan, with the right ownership, the right beneficiary structure, and the right coordination with trusts and other documents. When the two are designed together, the result is a plan that is both funded and directed.
The Core Insurance Tools and What Each One Actually Does
Life insurance is the most familiar tool, but it comes in several forms with very different roles. Term insurance provides pure protection for a defined period and is the least expensive way to cover a temporary need, such as the years until children are independent or a mortgage is paid off. Permanent insurance, including whole life and universal life, provides coverage for the insured’s lifetime and can build cash value that the policyholder may access. The choice between them is not about which is better in general. It is about which fits the specific need, and many families use both for different purposes.
For estate planning specifically, the most important structure is the irrevocable life insurance trust, commonly known as an ILIT. When a policy is owned by an ILIT rather than by the insured, the death benefit is generally excluded from the insured’s taxable estate, and the proceeds can be directed according to the trust’s terms rather than paid outright to beneficiaries. The trust can provide income to a surviving spouse, hold assets for children until they reach a certain age, protect the proceeds from creditors, and coordinate with the rest of the estate plan. The mechanics require care: the trust must be properly drafted and funded, the insured must not retain incidents of ownership, and the annual gift tax exclusion is typically used to fund premium payments through what are known as Crummey notices.
Other insurance tools play complementary roles. Disability insurance protects the family’s income during the insured’s working years, which is often the most valuable asset a young family has. Long-term care insurance addresses the cost of extended care, which can deplete a lifetime of savings in a few years and is one of the most common reasons families lose wealth across generations. Umbrella liability insurance protects against the lawsuits that can reach personal assets, and it is particularly important for families with visible wealth or business exposure. Each of these policies addresses a specific risk, and together they form a layer of protection that the estate plan can build on.
The key is to match the policy to the risk rather than to buy whatever is being marketed. A family with a large estate and a business that will need to be sold to pay taxes has a different need than a family with a modest estate and a paid-off home. A family with a child who has special needs has a different need than a family with adult children who are financially independent. Estate planning strategies should drive the insurance decisions, not the other way around, and the analysis should be revisited as the family’s circumstances change.
Structuring Ownership, Beneficiaries, and Trusts Correctly
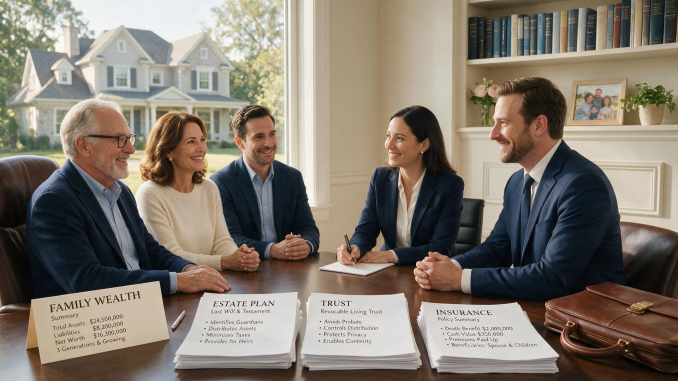
The single most important technical decision in life insurance estate planning is who owns the policy. If the insured owns the policy, the death benefit is included in the taxable estate, which can push the estate over the exemption threshold and create an unexpected tax bill. If the policy is owned by an ILIT, the death benefit is generally excluded, but the insured must give up control. If the policy is owned by a spouse, the exclusion depends on the spouse’s own estate and on whether the spouse survives. If the policy is owned by a business, the treatment depends on the entity structure and the purpose of the coverage. Each arrangement has consequences, and the right one depends on the family’s overall plan.
Beneficiary designations deserve as much attention as ownership. A policy that pays directly to beneficiaries bypasses the will and the trust, which means the estate plan’s carefully drafted distribution rules do not apply. That can be useful if the goal is to provide immediate liquidity, but it can be harmful if the goal is to protect the proceeds from creditors, divorce, or poor financial decisions. Naming a trust as beneficiary can preserve the protections of the estate plan, provided the trust is drafted to receive the proceeds properly and the policy is coordinated with the trust’s terms. The mismatch between beneficiary designations and estate planning documents is one of the most common sources of unintended outcomes.
Funding the ILIT correctly is another area where plans often fail. The trust needs cash to pay premiums, and the standard method is for the grantor to make annual gifts to the trust, which are then used to pay the premiums. Those gifts need to qualify for the annual exclusion, which typically requires giving the beneficiaries a limited right to withdraw the contribution for a period of time, known as a Crummey power. The notices documenting that right must be sent and retained, because the IRS can challenge the exclusion if the formalities are not followed. This is administrative work, but it is what makes the structure hold up under scrutiny.
The ownership and beneficiary structure should also be coordinated with the rest of the estate plan. A policy owned by an ILIT may need to be coordinated with a revocable trust, a family limited partnership, or a charitable strategy. A policy intended to provide liquidity for estate taxes should be sized to the expected tax bill, which requires an accurate valuation of the estate and a realistic projection of future growth. A policy intended to equalize inheritances among children should be coordinated with the distribution provisions of the will or trust. Generational wealth protection works best when every piece of the plan is designed with the others in mind.
Beyond Life Insurance: Protecting the Family Against Other Risks
Life insurance addresses the risk of death, but it is not the only risk that threatens generational wealth. Disability, long-term care, liability, and business risks can all erode a family’s assets, and each requires its own response. Disability insurance replaces income if the insured cannot work, which is essential for younger families whose earning capacity is their most valuable asset. Long-term care insurance addresses the cost of extended care, which can run into hundreds of thousands of dollars and is often underestimated. Business insurance, including key-person coverage and buy-sell funding, protects the family’s interests in a closely held company.
Liability insurance is particularly important for families with significant visible wealth. Umbrella policies sit on top of auto, homeowners, and other liability coverage and provide additional protection against large claims. For families with rental properties, board positions, or public profiles, the exposure can be substantial, and the cost of coverage is usually small relative to the protection it provides. The policy should be coordinated with the family’s asset protection strategy, because insurance and legal structures work best when they reinforce each other rather than operate in isolation.
Long-term care deserves special attention because it is one of the most common ways that wealth is lost across generations. The cost of care can deplete a lifetime of savings in a few years, and the burden often falls on the surviving spouse or the adult children. Long-term care insurance, hybrid life and long-term care policies, and careful planning around Medicaid eligibility all play a role. The right approach depends on the family’s health, their assets, and their preferences, but the conversation should happen well before care is needed, because options narrow as health declines.
The family should also consider the role of insurance in business succession. A buy-sell agreement funded by life insurance ensures that the surviving owners can buy out a deceased owner’s interest without draining the company’s cash or forcing a sale. Key-person insurance protects the business against the loss of a critical employee. Business overhead expense insurance covers fixed costs during a period of disability. These policies are not glamorous, but they are often the difference between a business that survives a transition and one that does not. Family wealth preservation depends on protecting the sources of wealth, not just the wealth itself.
Common Mistakes and the Coordination That Prevents Them
The most common mistake is buying insurance without integrating it into the estate plan. A policy that is owned by the insured, payable to the estate, or funded with outdated beneficiary designations can create tax problems, probate delays, and unintended outcomes. The fix is to coordinate the policy with the estate attorney, the CPA, and the financial advisor, and to review the ownership and beneficiary structure every few years as the family’s circumstances change. The review should also confirm that the policy is still performing as expected, that the premiums are sustainable, and that the coverage amount is still appropriate.
A second mistake is underinsuring. Families often buy coverage based on a rough estimate and never revisit it as their wealth, income, and obligations grow. A policy that was adequate ten years ago may be far too small today, especially if the family has acquired a business, a second home, or additional dependents. The coverage amount should be recalculated periodically, with a clear understanding of what the policy is intended to fund: estate taxes, income replacement, debt repayment, education, charitable gifts, or a combination of these.
A third mistake is overcomplicating the structure. Some families create multiple trusts, policies, and entities in an effort to optimize every detail, and end up with a plan that is difficult to administer and expensive to maintain. The best plans are usually the ones that are simple enough to operate correctly and flexible enough to adapt as circumstances change. Complexity should be justified by a clear benefit, and the family should understand how each piece of the plan works before it is put in place.
The final piece is communication. A plan that the family does not understand is a plan that will not be executed as intended. The spouse, the adult children, and the trusted advisors should all know what the plan is designed to do, who is responsible for each part, and what to do when the time comes. A short written summary, a family meeting, and a clear point of contact can make the difference between a plan that works and one that creates confusion at exactly the moment it is needed most. Insurance and estate planning, done together and reviewed regularly, give a family the best chance of preserving what it has built for the generations that follow.