Why the Exit Is the Whole Point of the Investment
Private equity investors tend to spend most of their attention on the buy side. They analyze the target company, the management team, the market, and the price. That work matters, but it is only half of the equation. The return on any private equity investment is determined by two numbers: what the fund pays to acquire the company and what it receives when it sells. The second number is where private equity exit strategies come into play, and it is where the difference between a good fund and a mediocre one is often made. A fund that buys well but cannot exit profitably will underperform, and a fund that executes exits well can generate strong returns even on investments that looked ordinary at the time of purchase.
The exit is also the moment when the fund’s investors actually receive their money back. Private equity commitments are locked up for years, and the distributions that investors receive come from exits. That means the timing and quality of exits have a direct impact on the fund’s realized returns and on the investor’s ability to redeploy capital. A fund that exits early and well may return capital in five or six years, while a fund that struggles to exit may hold assets for a decade or more, which reduces the internal rate of return and ties up investor capital for longer than expected.
The exit is also where the fund’s value-creation work is tested. A private equity fund that has improved a company’s operations, grown its revenue, and strengthened its management team should be able to sell it at a higher multiple than it paid. A fund that has not done that work may find that the company is worth no more than it was at purchase, or less. The exit is the moment of truth, and it reveals whether the fund’s strategy actually created value or whether it simply rode a rising market.
For families considering a commitment to a private equity fund, understanding the exit strategy is essential. A fund that has a clear, repeatable approach to exits is more likely to deliver consistent returns than one that relies on luck or on a favorable market environment. The family should ask the fund how it plans to exit each investment, what buyers it expects to sell to, and what conditions would cause it to delay or change its exit plans. Those questions reveal a great deal about the fund’s discipline and its realism. Private equity investment lifecycle is not complete until the exit happens, and the quality of that exit determines the return.
The Main Exit Routes and What Each One Requires
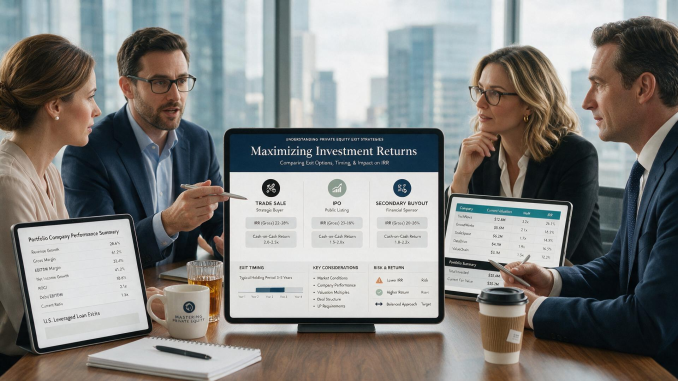
The most common exit route is a sale to a strategic buyer, which is typically a larger company in the same industry or an adjacent one. Strategic buyers are often willing to pay a premium because they can realize synergies, such as cost savings or cross-selling opportunities, that a financial buyer cannot. That premium can translate into a higher return for the private equity fund, which is why strategic sales are often the preferred exit route. The challenge is that strategic buyers are not always available, and the pool of potential buyers may be limited by antitrust considerations, industry consolidation, or the buyer’s own strategic priorities.
A second route is a sale to another private equity firm, often called a secondary buyout. That route has become increasingly common as the private equity industry has grown and as funds have accumulated large portfolios of companies that need to be exited. Secondary buyouts can be attractive because they allow the selling fund to exit at a reasonable price without relying on a strategic buyer, and they allow the buying fund to acquire a company that has already been through a period of professional management. The challenge is that secondary buyouts may not generate the same premium as strategic sales, and the buying fund may be unwilling to pay a price that reflects the full value of the company.
A third route is an initial public offering, which involves selling shares to the public through a stock exchange listing. An IPO can generate a strong return if the market is receptive and the company has a compelling story, but it is also the most complex and uncertain exit route. The process requires extensive preparation, regulatory compliance, and investor relations work, and the timing depends on market conditions that the fund cannot control. An IPO also typically involves a lock-up period during which the fund cannot sell its remaining shares, which extends the time to full liquidity. Mergers and acquisitions and IPOs are the two most visible exit routes, but they are not the only ones, and the right choice depends on the company, the market, and the fund’s objectives.
A fourth route is a recapitalization, which involves the company taking on new debt to pay a dividend to the private equity fund. That route allows the fund to return capital to its investors without selling the company, and it can be attractive when the market for exits is slow. The challenge is that a recapitalization increases the company’s debt load, which can be risky if the company’s cash flows decline. A fund that relies too heavily on recapitalizations may be creating risk for the company and for its investors, and the family should be cautious about a fund that uses that route frequently.
How Exit Timing and Market Conditions Affect Returns
The timing of an exit has a significant impact on the return. A fund that exits at the top of a market cycle may receive a higher multiple than one that exits during a downturn, even if the underlying company is the same. That means the fund’s ability to time exits is an important source of value, and the family should understand how the fund approaches that challenge. Some funds use a disciplined process that sets target exit windows and holds to them regardless of market conditions, while others are more opportunistic and may delay an exit if they believe the market will improve. Both approaches have merit, but the family should understand which one the fund uses and whether it is consistent with the fund’s stated strategy.
Market conditions also affect the availability of buyers. During a strong market, strategic buyers are more willing to pay premium prices, and IPO windows are more open. During a downturn, buyers become more cautious, and the pool of potential buyers may shrink. A fund that has a diversified portfolio of companies may be able to exit some of them even in a difficult market, while a fund that is concentrated in a single sector or a single company may be more exposed to market conditions. The family should consider the fund’s portfolio concentration and its exposure to cyclical industries, because those factors affect the fund’s ability to exit on favorable terms.
The exit environment also affects the fund’s ability to return capital to its investors. A fund that is unable to exit its investments may be forced to extend its holding period, which reduces the internal rate of return and delays distributions. That is why Private equity liquidity events are so important. The family should understand the fund’s expected exit timeline and should be prepared for the possibility that exits may be delayed. A fund that has a clear plan for exits and a track record of executing them is more likely to deliver on its promises than one that has no clear plan or that has a history of delaying exits.
The exit environment also affects the fund’s ability to raise new capital. A fund that has successfully exited its investments and returned capital to its investors is more likely to attract new commitments than one that has struggled to exit. That means the exit strategy is not just about the current fund’s returns. It is also about the fund’s ability to raise future funds, which affects the manager’s long-term viability and the family’s ability to continue investing with the manager in the future.
What Returns Really Look Like and How to Evaluate Them
Private equity returns are typically reported using two metrics: the internal rate of return, which measures the annualized return on the fund’s investments, and the multiple of invested capital, which measures the total return relative to the amount invested. Both metrics are useful, but they measure different things. The internal rate of return is sensitive to the timing of cash flows, so a fund that returns capital quickly may show a higher IRR than one that returns capital slowly, even if the total return is similar. The multiple of invested capital is less sensitive to timing, so it is a better measure of the fund’s overall performance. The family should look at both metrics and should understand how they are calculated before comparing funds.
The family should also distinguish between realized and unrealized returns. Realized returns are based on actual exits and represent cash that has been returned to investors. Unrealized returns are based on the estimated value of investments that have not yet been exited, and they may not reflect the true economic value of those investments. A fund that reports strong returns based largely on unrealized gains may be more risky than one that reports strong returns based on realized gains, because the unrealized gains may not materialize if the market changes or if the company’s performance deteriorates.
The family should also consider the fund’s track record across multiple vintages, not just the best-performing one. A fund that has delivered strong returns in one vintage may have benefited from a favorable market environment, and its performance may not be repeatable. A fund that has delivered consistent returns across multiple vintages is more likely to be a reliable partner over time. The family should also consider the fund’s performance relative to its peers, because a fund that outperforms in a strong market may underperform in a weak one, and the family should understand how the fund’s returns compare to other funds with similar strategies.
The family should also consider the fund’s fees and expenses, because those costs reduce the net return to investors. A fund that reports a strong gross return may have a much lower net return once fees are taken into account, and the family should focus on the net return because that is what it actually receives. The family should also consider the fund’s use of leverage, because leverage can amplify returns but also amplify losses, and a fund that relies heavily on leverage may be more vulnerable to a downturn than one that uses leverage more conservatively.
Common Mistakes and the Long View
The most common mistake is focusing on the buy side and ignoring the exit. Families often evaluate a private equity fund based on its ability to source and acquire companies, without considering whether the fund has a credible plan for exiting those investments. A fund that buys well but cannot exit profitably will underperform, and the family should ask the fund how it plans to exit each investment and what evidence it has that those plans are realistic.
Another common mistake is underestimating the time required to exit. Private equity investments can take years to mature, and the exit process itself can take months or longer. A family that expects quick returns may be disappointed, and a family that needs liquidity in the near term should not commit capital to private equity. The family should be prepared to hold its investments for the full term of the fund and should maintain a reserve of liquid assets to cover unexpected needs.
A third mistake is ignoring the interaction between the exit strategy and the fund’s overall portfolio. A fund that is concentrated in a single sector may be more exposed to market conditions, and a fund that has a large number of investments in the same stage of development may find that its exits are bunched together, which can reduce the fund’s ability to time them optimally. The family should consider the fund’s portfolio construction and should understand how the fund manages the timing of its exits.
Ultimately, the exit strategy is one of the most important factors in private equity returns, and it deserves as much attention as the buy side. A fund that has a clear, repeatable approach to exits, a track record of executing them, and a realistic view of market conditions is more likely to deliver strong returns than one that does not. The families that do well with private equity are the ones that understand this and that evaluate funds on their ability to exit as well as their ability to buy. That discipline is what separates a thoughtful investor from a hopeful one, and it is the foundation of any successful private equity program.