Two Branches of the Same Tree, With Very Different Fruit
Private equity and venture capital are often discussed as if they were interchangeable, and in casual conversation they sometimes are. Both invest in companies that are not publicly traded. Both pool capital from institutional and high-net-worth investors. Both aim to generate returns by growing the value of the underlying businesses and eventually exiting. But the similarities end quickly once you look at how the money is actually deployed, what kind of companies each asset class targets, and what kind of risk the investor is signing up for. Understanding the difference matters, because a family that is comfortable with one is not necessarily comfortable with the other, and the two play very different roles in a broader alternative investment comparison.
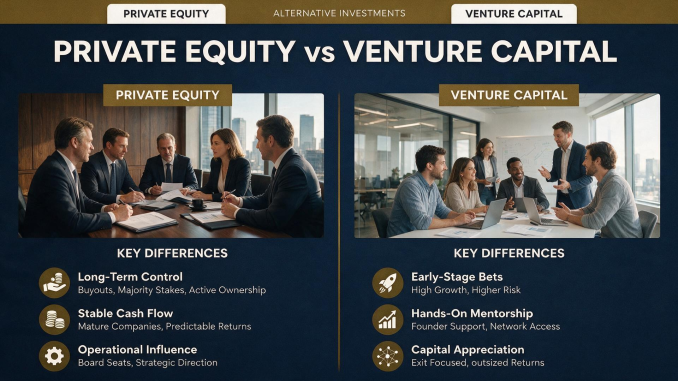
The simplest way to frame the distinction is by stage and by control. Venture capital invests in young companies, often before they have meaningful revenue, and typically takes a minority stake with limited operational control. Private equity invests in mature companies, often with established cash flows, and typically takes a controlling stake with the ability to direct strategy and management. Venture capital is a bet on a future that does not exist yet. Private equity is a bet on improving something that already works. Those two bets require different skills, different time horizons, and different tolerances for failure.
The risk and return profiles reflect that difference. Venture capital follows a power-law distribution: most investments return little or nothing, a few return a moderate amount, and a small number return many times the original investment. The entire return of a venture fund often comes from one or two companies in the portfolio. Private equity returns are more normally distributed, with most investments producing moderate gains and a smaller number producing large gains or losses. That means venture capital is higher variance, and the difference between a good fund and a mediocre fund is enormous. Private equity is lower variance, and the difference between a good fund and a mediocre fund is meaningful but not as extreme.
The operational demands also differ. Venture capital investors typically work closely with founders, providing guidance, introductions, and strategic advice, but they do not run the company. Private equity investors often install new management, restructure operations, refinance debt, and make decisions that affect every part of the business. That hands-on approach requires a different skill set, a different team structure, and a different relationship with the companies being owned. For families considering Private market investments, the choice between the two categories should reflect not just the return profile but also the kind of exposure the family wants and the kind of risk it can tolerate.
How Each Strategy Actually Makes Money
Private equity investment strategies generally fall into a few broad categories. Buyouts involve acquiring a controlling stake in a mature company, often using leverage, and working to improve operations, grow revenue, or reposition the business before selling it or taking it public. Growth equity involves investing in companies that are already generating revenue and need capital to scale, without taking full control. Distressed investing involves buying the debt or equity of companies in financial trouble and working through a restructuring. Mezzanine and private credit involve lending to companies that need capital but do not want to sell equity. Each of these strategies has its own risk and return profile, and the best private equity firms tend to specialize rather than spread across all of them.
Venture capital operates on a different logic. A venture fund typically invests in a portfolio of early-stage companies, knowing in advance that most will fail. The fund’s return depends on identifying the small number of companies that will become category leaders, and on having the conviction to hold them through the inevitable ups and downs. The work involves sourcing deals, evaluating founders and markets, and supporting portfolio companies as they grow. The best venture firms have deep networks, strong reputations, and a track record of backing successful founders, which gives them access to the best deals. That access is the source of their edge, and it is difficult for new entrants to replicate.
Exit strategies also differ. Private equity exits are typically through a sale to a strategic buyer, a sale to another private equity firm, or an initial public offering. The timing is often more predictable because the companies are mature and have established financials. Venture capital exits are less predictable, because the companies are younger and the path to liquidity is longer and more uncertain. A venture-backed company might be acquired in three years, or it might take a decade to reach an IPO, or it might never reach either. The illiquidity and uncertainty are part of the asset class, and investors need to be prepared for both.
The fee structures are similar on the surface but different in practice. Both categories typically charge a management fee of one to two percent and a performance fee of around twenty percent, often with a hurdle rate. The difference is in the carry and the timing. Venture funds often have longer investment periods and longer fund lives, which means the fees are paid over a longer period. Private equity funds often return capital more quickly, which means the performance fee is realized sooner. Those differences affect the net return to investors, and they should be factored into any comparison. Venture capital investing is not simply private equity with younger companies. It is a distinct asset class with its own economics and its own risks.
Risk, Diversification, and What Each Category Demands From Investors
Diversification works differently in each category. In private equity, a portfolio of ten to fifteen companies can provide meaningful diversification, because the outcomes are more normally distributed. In venture capital, a portfolio of ten to fifteen companies may still be dominated by a single winner, because the power-law distribution means that one company often accounts for the majority of the fund’s return. That is why venture investors often spread their commitments across multiple funds and multiple vintages, rather than trying to pick a single winner. The goal is not to avoid losses on individual companies, because losses are expected. The goal is to ensure that the fund has enough shots on goal to capture the one or two companies that will drive the return.
The time horizon is another important difference. Private equity funds typically have a fund life of seven to ten years, with capital returned over that period. Venture funds often have longer fund lives, sometimes ten to twelve years or more, because the companies in the portfolio take longer to mature. That means venture capital requires a longer commitment from investors, and the illiquidity is more pronounced. A family that needs liquidity in the next five years should not be committing to venture capital, even if the fund’s track record is strong.
The skill required to evaluate each category is also different. Private equity due diligence focuses on financials, operations, management, and market position. The investor needs to understand how the company makes money, what the competitive dynamics are, and whether the management team can execute. Venture capital due diligence focuses on the founders, the market opportunity, the technology, and the potential for exponential growth. The investor needs to understand whether the company is solving a real problem, whether the team has the ability to execute, and whether the market is large enough to support a venture-scale outcome. Those are different questions, and they require different analytical frameworks.
The failure modes are different as well. Private equity investments can fail because of excessive leverage, operational problems, or a downturn in the industry. Venture capital investments can fail because the market did not materialize, the technology did not work, or the team could not execute. The investor should understand the specific risks of each category and should be comfortable with the possibility of loss. Neither asset class is suitable for investors who cannot afford to lose some or all of their capital, and both require a long-term perspective that most public market investors are not accustomed to.
Which One Fits Which Kind of Investor
The choice between private equity and venture capital is not about which one is better. It is about which one fits the investor’s goals, risk tolerance, and time horizon. A family that is looking for moderate returns with lower variance, predictable exits, and a shorter time horizon may be better suited to private equity. A family that is looking for higher returns with higher variance, a longer time horizon, and a tolerance for losses on individual investments may be better suited to venture capital. A family that is looking for both may allocate to both, with different weights depending on its overall portfolio and its appetite for risk.
The family’s existing exposure also matters. A family that already owns a mature operating business may find that private equity is a natural extension, because the skills and relationships overlap. A family that has experience with early-stage companies, either as founders or as angel investors, may find that venture capital is a better fit. A family with no experience in either category should start slowly, with a small allocation to a diversified fund or a fund-of-funds, and should build its knowledge before committing larger amounts.
The manager selection process is also different. Private equity managers are often evaluated on their track record, their operational expertise, and their ability to source and execute deals. Venture capital managers are often evaluated on their network, their reputation with founders, and their ability to identify and support breakout companies. The due diligence questions are different, and the investor should use different criteria for each category. A manager who is excellent in one category is not necessarily excellent in the other, and the family should not assume that a strong track record in private equity translates to venture capital.
The allocation between the two should reflect the family’s overall portfolio and its objectives. A common approach is to allocate a portion of the alternative portfolio to private equity for stable, moderate returns and a smaller portion to venture capital for higher-risk, higher-reward exposure. The exact split depends on the family’s circumstances, but the principle is that the two categories serve different purposes and should be sized accordingly. Private equity vs venture capital is not a choice between good and bad. It is a choice between two different tools, each of which can play a valuable role in the right portfolio.
Common Mistakes and a Balanced Approach
The most common mistake is treating the two categories as if they were the same. Families often assume that because they understand private equity, they understand venture capital, and they apply the same due diligence, the same allocation logic, and the same expectations. That assumption leads to disappointment, because the two categories behave very differently. The fix is to recognize the differences and to build separate processes for each, with different criteria, different expectations, and different risk management.
Another common mistake is over-allocating to one category based on recent performance. Venture capital had a strong decade through the early 2020s, and many families increased their allocations as a result. That is a natural response, but it can lead to concentration and to disappointment when the cycle turns. The right approach is to set a target allocation based on the family’s goals and risk tolerance, and to rebalance toward that target rather than chasing performance.
A third mistake is underestimating the illiquidity and the operational burden. Both categories require a long-term commitment, and both require ongoing monitoring, reporting, and administrative work. Families should be realistic about the time and resources required, and they should build in a buffer of liquid assets to cover unexpected needs. A family that is forced to sell a private market position at a discount has lost much of the benefit of the asset class, regardless of how well the underlying investments performed.
Ultimately, private equity and venture capital are both valuable tools for families that understand them and can afford the risks. The key is to approach them with discipline, to diversify across managers and vintages, to size allocations appropriately, and to maintain realistic expectations. Families that do this well tend to find that the two categories complement each other, with private equity providing stability and venture capital providing growth. Families that approach them casually often find that the lessons are expensive. The difference is in the preparation, and the preparation is worth the effort.